At 19, David Nandwa Saw a Payment Problem. What Is HoneyCoin Building to Solve It?
HoneyCoin, founded by David Nandwa, is building financial infrastructure connecting African payment rails with stablecoins and global finance.
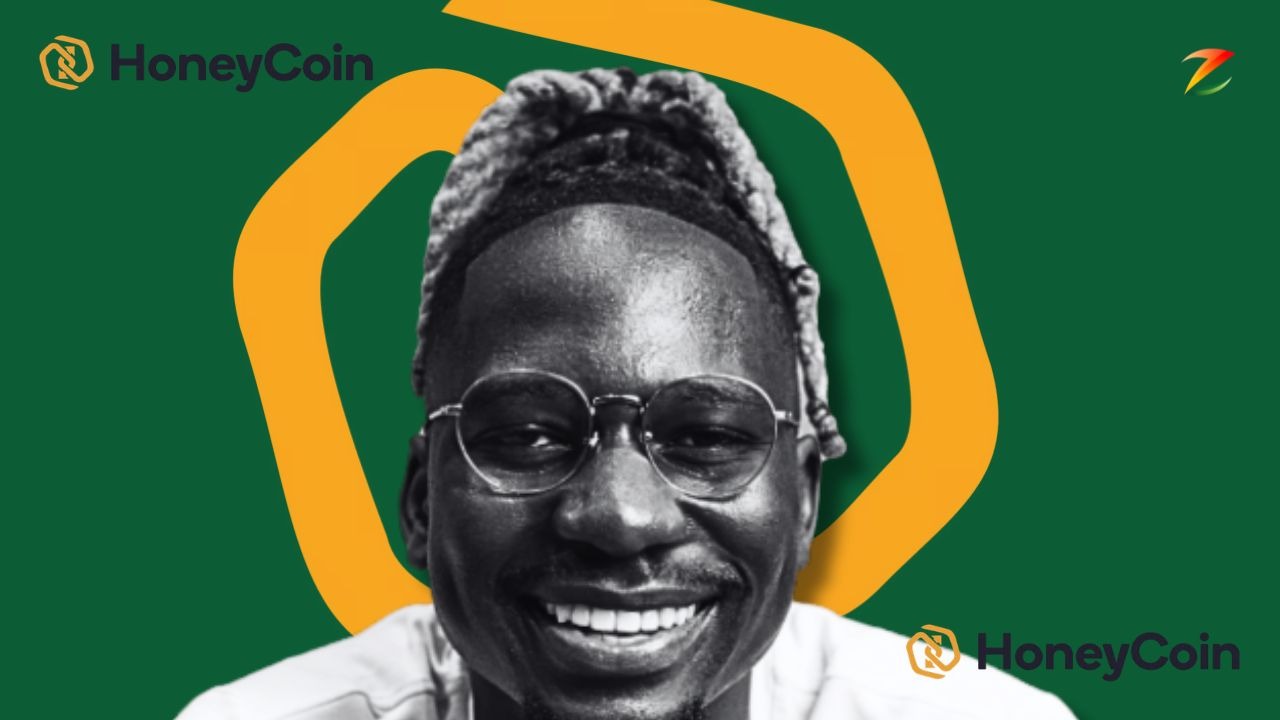
At 19, David Nandwa founded HoneyCoin in 2020, driven by a belief that one of the problems holding back Africa’s growth was its fragmented financial infrastructure. The company’s operations and broader expansion developed from 2021, as Nandwa began building the financial infrastructure business around that conviction.
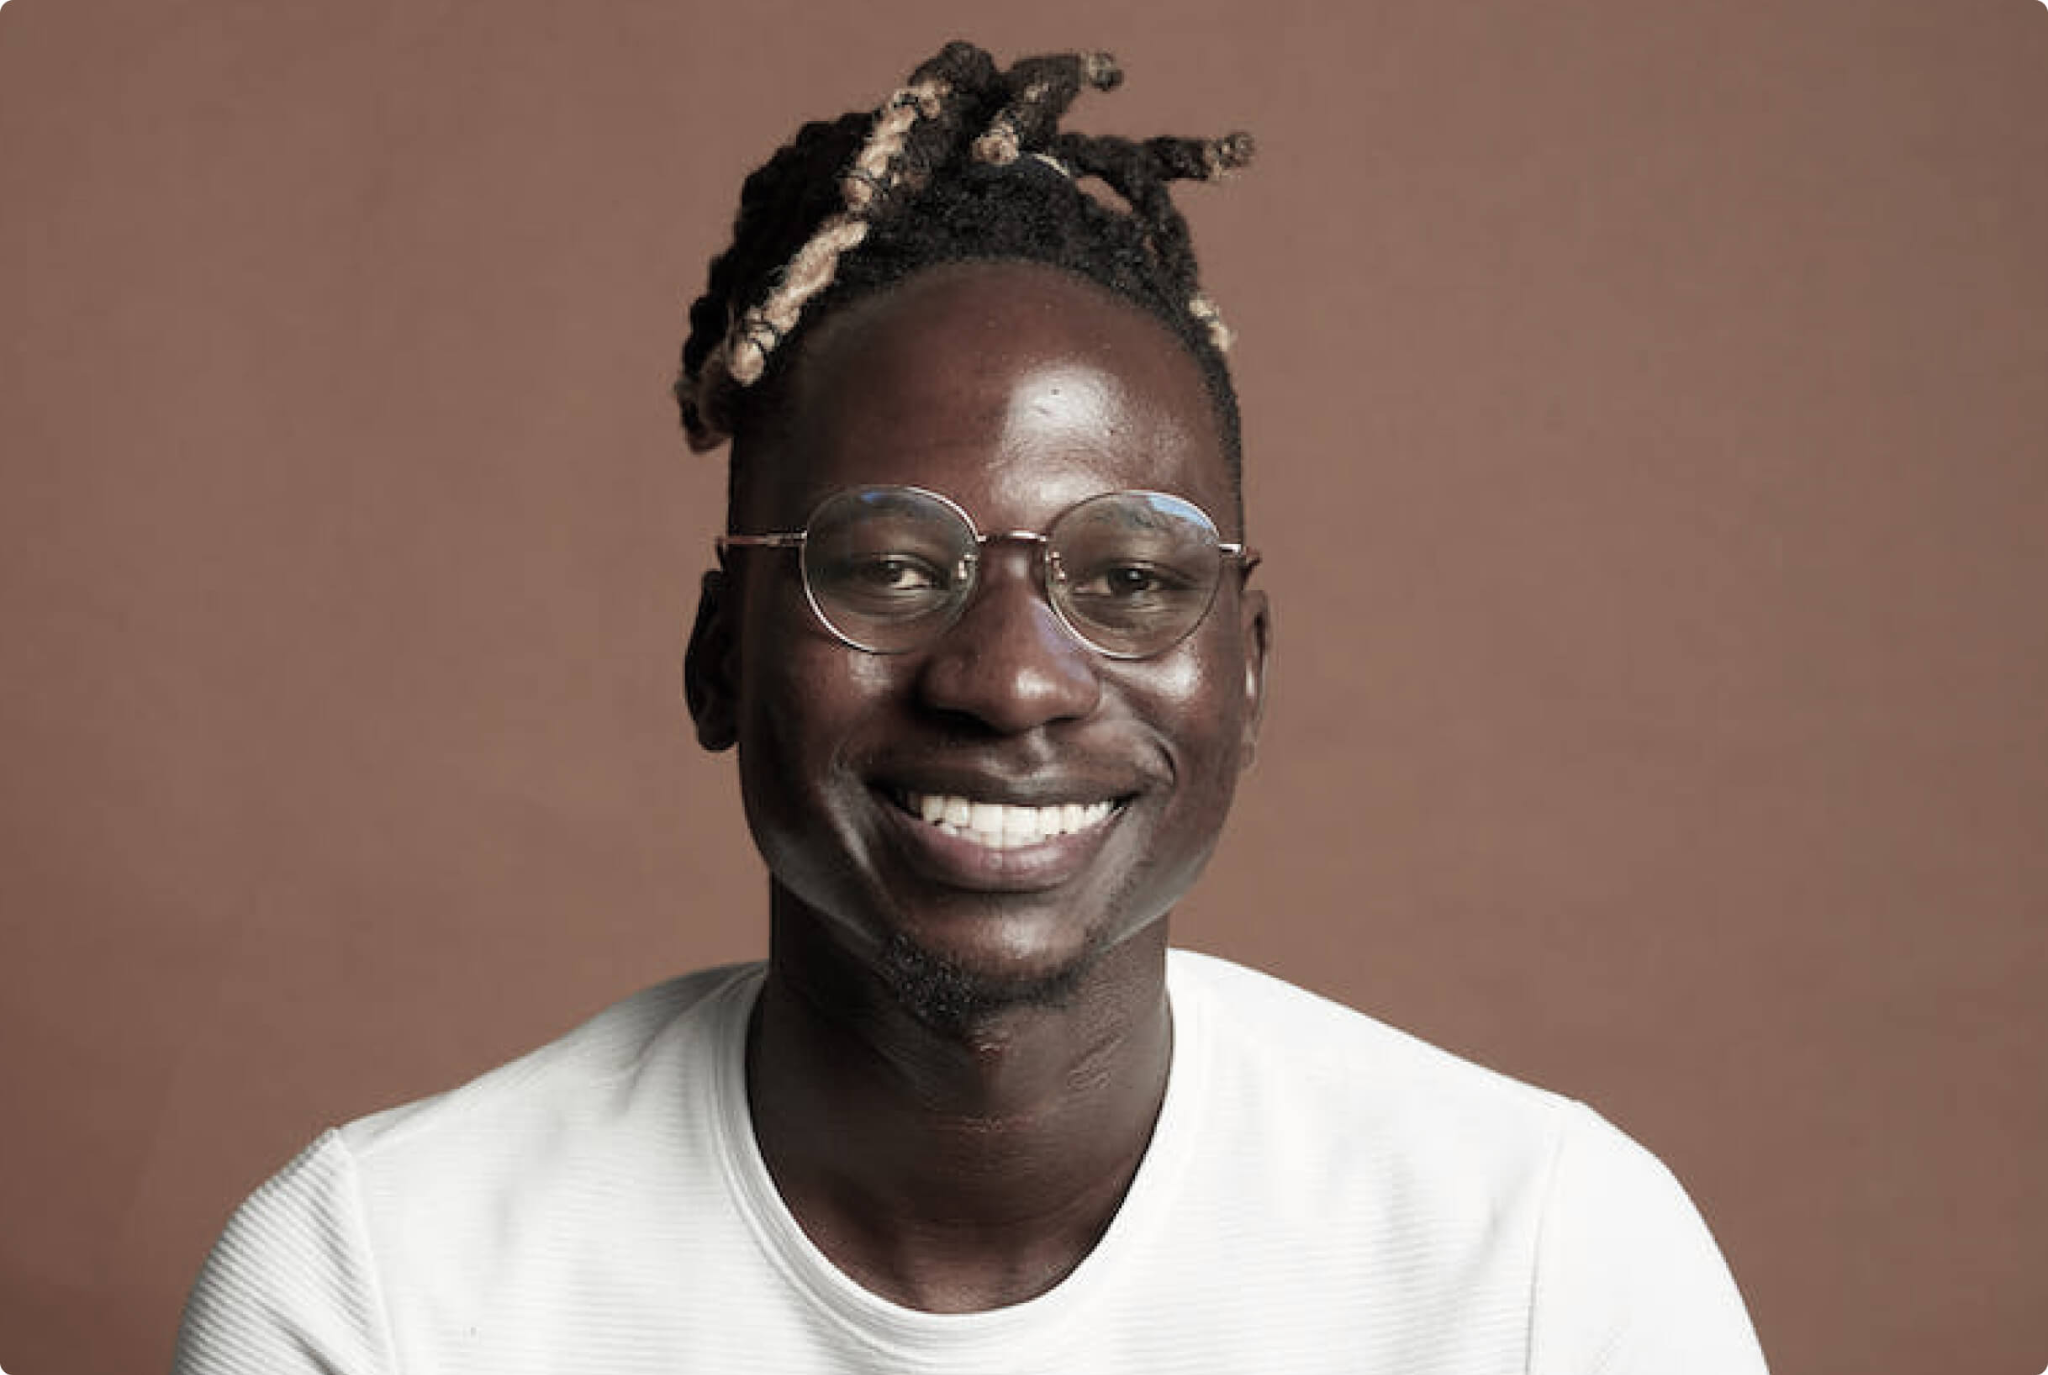
Now 25, Nandwa leads HoneyCoin, the financial infrastructure company he founded in 2020 to connect the financial systems Africans already use with newer technologies such as stablecoins, blockchain and AI.
In an interview about HoneyCoin’s journey, Nandwa described himself as a 19-year-old who was “naive enough” to believe he could help solve some of Africa’s financial problems, but ambitious enough to keep pursuing the idea years later.
That ambition has developed into a company focused on making it easier for businesses to move money across African markets and between Africa and the rest of the world.
Building a Bridge Between Old and New Finance
For Nandwa, the problem begins with fragmentation. Banks, telecommunications companies, card networks and mobile-money providers operate across different systems, currencies and regulatory environments.
A business expanding into several African markets can therefore face separate integrations, payment methods and compliance requirements simply to move money between customers and markets.
HoneyCoin is attempting to put those different rails behind a single infrastructure layer.
Its platform supports collections and payouts across African markets, with payment methods including bank transfers, mobile money, cards and stablecoins. Its infrastructure also supports USDC and USDT, allowing businesses to move between local currencies and dollar-pegged digital assets.
Nandwa describes the company's role as connecting the “old world” of telcos, banks and card networks with the “new world” of stablecoins, blockchain and AI.
The objective is not necessarily to replace existing financial systems, but to connect them in ways that can reduce the cost and time involved in payments.
For businesses, that could mean fewer integrations, faster settlement and a simpler way to collect or send money across different markets.
The Scale Behind HoneyCoin
According to Nandwa, HoneyCoin currently processes more than $200 million in monthly volume across 29 African countries. He said the company serves businesses including NALA, TAF, CAPSEND, GEGE and TeraPay, and is licensed in six African markets.
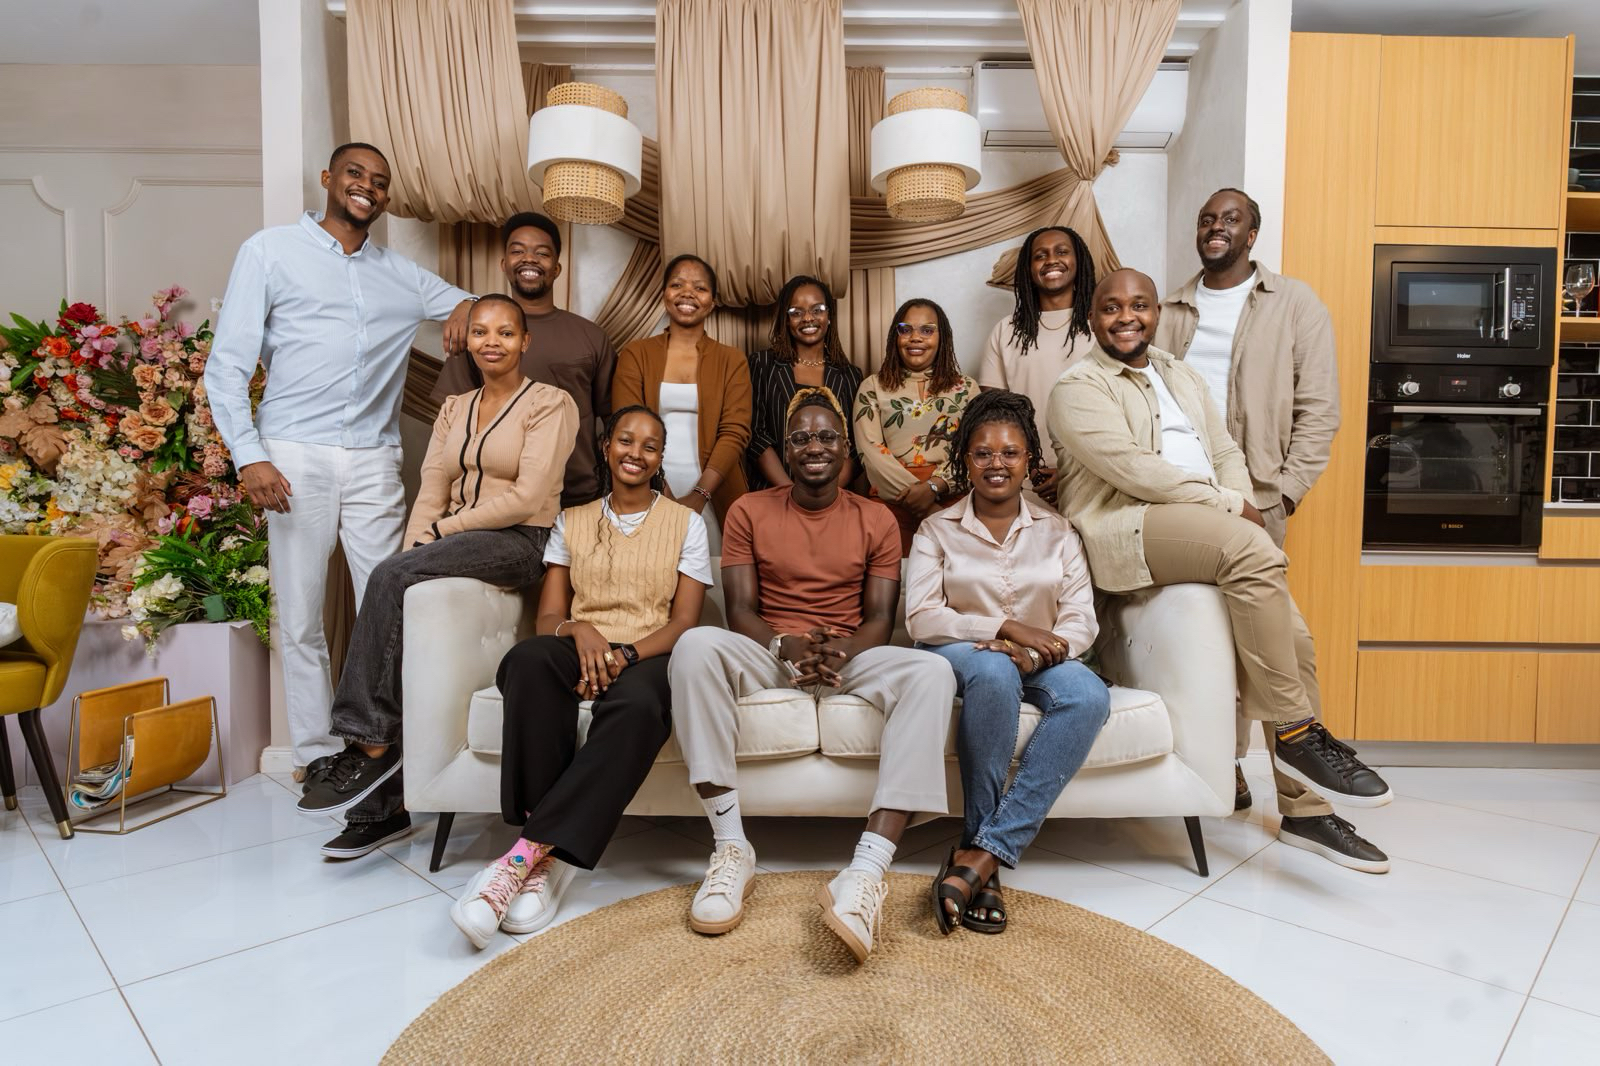
Nandwa also said HoneyCoin is expected to secure 10 additional licences by the end of the year, with roughly 50 people working at the company.
HoneyCoin’s public documentation lists payment coverage across 26+ markets and currencies, including African markets as well as countries in Europe and North America. Its African infrastructure includes bank and mobile-money rails across markets such as Nigeria, Kenya, Ghana, Tanzania, Uganda, Rwanda, Zambia, Ethiopia, and several Francophone African countries.
The startup has also attracted institutional investment. In 2025, HoneyCoin announced a $4.9 million funding round co-led by Flourish Ventures and Visa Ventures, with participation from TLcom Capital, Stellar Development Foundation, Lava, Musha Ventures, 4DX Ventures and Antler.
For Nandwa, however, reaching this stage has involved more than raising capital and expanding into new markets.
He identified regulation and distribution as two of HoneyCoin’s biggest challenges. According to Nandwa, the company began building before clear regulatory structures existed, and he has experienced bank-account closures during the company's development.
His broader argument is that innovation can sometimes arrive before the regulatory framework designed to govern it.
What Africa Could Gain
The potential value of HoneyCoin extends beyond cryptocurrency.

African businesses increasingly trade across borders, but payment systems remain fragmented. A company operating in Nigeria may need a different payment rail in Kenya, another in Ghana, and another in Côte d’Ivoire. Currency conversion, settlement times, compliance, and local infrastructure can all add friction to those transactions.
HoneyCoin’s model attempts to make those differences less visible to businesses.
Its platform allows companies to connect to multiple payment rails, while customers can use locally familiar payment methods and businesses can settle through local currencies or stablecoins.
But the company is entering markets where the economics can be difficult.
Nandwa singled out Nigeria as the hardest market for HoneyCoin to enter, pointing to its large economy and population alongside high price sensitivity, low transaction margins, and a challenging regulatory environment.
That tension could become increasingly important as HoneyCoin expands.
The company is building on the idea that Africa’s financial future does not have to belong entirely to traditional banking or entirely to blockchain. Instead, Nandwa sees an opportunity for banks, telcos, card networks, mobile money and stablecoins to operate together.
If HoneyCoin succeeds in making those connections easier, its impact could extend beyond cryptocurrency users to businesses trying to trade, collect payments, and move money across a continent where financial borders remain difficult to navigate.